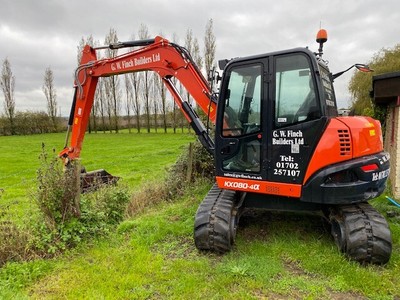
It's started...

doobin

doobin

Well-known member
Can't have been much more than the asking surely?

Wonder how low they'll go?
 
Regy53

Regy53

I like cake
Genuinely, i dont think it has started.

Its pretty busy and not much kit is being sold at the moment. To much government money for nothing floating about.

For example with that... Borrow the £50k Bounce back, clear the finance if there is any and have a year without a payment
 
Furniss

Furniss

Well-known member
Stickered up pretty well if they only bought it for the one project and @ 90hrs ..... wasnt a big project - might have been better to hire one for the 2 weeks :)
 
JD450A

JD450A

Feral as Fk 🐾
Stickered up pretty well if they only bought it for the one project and @ 90hrs ..... wasnt a big project - might have been better to hire one for the 2 weeks :)
I hate people that sticker the back window lines of sight...
 
Furniss

Furniss

Well-known member
Yep - I have a mate with some horrendus advertising stuff that you can see out but not in .... fecking dangerous if you ask me.
I have some in my machines but up high in one and down low in other - well out of line of sight.
 
GazCro

GazCro

Well-known member
Genuinely, i dont think it has started.

Its pretty busy and not much kit is being sold at the moment. To much government money for nothing floating about.

For example with that... Borrow the £50k Bounce back, clear the finance if there is any and have a year without a payment
All this loan carry on isn't exactly clear though i was under the impression you couldn't use it to pay off existing finance yet people seem to be intending doing this. I guess it may be down to how well policed it is. I fear people may get bitten further down the line by this.
 
TiltyShaun

TiltyShaun

Well-known member
My guess is someone thought it would be a good idea to buy it to save some tax. 90hrs later it might not seem to have been such a good idea!!! Not sure of what they cost new but it would need to be a decent differential to tempt most people......unles of course they cant wait for whatever the current lead time is. For me, still happy with the 4 year old Kobelco that was have that price!!!
 
GazCro

GazCro

Well-known member
My guess is someone thought it would be a good idea to buy it to save some tax. 90hrs later it might not seem to have been such a good idea!!! Not sure of what they cost new but it would need to be a decent differential to tempt most people......unles of course they cant wait for whatever the current lead time is. For me, still happy with the 4 year old Kobelco that was have that price!!!
I would reckon be 60k new for a round number, id be surprised if it's more than 2k either side of that.
 
Regy53

Regy53

I like cake
All this loan carry on isn't exactly clear though i was under the impression you couldn't use it to pay off existing finance yet people seem to be intending doing this. I guess it may be down to how well policed it is. I fear people may get bitten further down the line by this.

Your not supposed to i believe... People are buying diggers with it for a fact..
 
Lancs Lad

Lancs Lad

Well-known member
Get em bought ...HMRC haven't a hope of policing all this stuff ...they have publicly admitted it been cutting back for years I'm reliably informed ...as long as you not been doing anything silly that will attract attention crack on...that's if u can get one...we trying with two banks both being complete pain in the arse .btw you can get one loan per ltd company...🙄👌😉
As long as youve been smart and spread turnover about a bit your laughing..👍
 
Lancs Lad

Lancs Lad

Well-known member
The way I look at it ...it's our dough that we gave to RBS in the GFC anyway...bastards are being tight and awkward as they come. One switched on FD I know well has been tapping up MPs he's that pissed off with RBS behaviour in this crisis. They owe their survival to the taxpayer FFS.
 
GazCro

GazCro

Well-known member
Get em bought ...HMRC haven't a hope of policing all this stuff ...they have publicly admitted it been cutting back for years I'm reliably informed ...as long as you not been doing anything silly that will attract attention crack on...that's if u can get one...we trying with two banks both being complete pain in the arse .btw you can get one loan per ltd company...🙄👌😉
As long as youve been smart and spread turnover about a bit your laughing..👍
As long as they don't invest in more staff, they'll need to do something to claw all this back in the long term.
 
Lancs Lad

Lancs Lad

Well-known member
As long as they don't invest in more staff, they'll need to do something to claw all this back in the long term.
Aye but you ever met them twats? More tea breaks than council workers and probably all want furloughing the minute they start...complete joke.
 
V8Druid

V8Druid

do it as well as you can,but learn to do it better
Aye but you ever met them twats? More tea breaks than council workers and probably all want furloughing the minute they start...complete joke.
they got no sense of humor for sure .... never seen one smile on a visit ... especially the VAT man
 
craig

craig

Well-known member
All this loan carry on isn't exactly clear though i was under the impression you couldn't use it to pay off existing finance yet people seem to be intending doing this. I guess it may be down to how well policed it is. I fear people may get bitten further down the line by this.
I was told the same initially, then got told it was ok.
With a little searching it seems to be confusion between the coronavirus business interruption loan scheme.

What is the difference between CBILS and the Bounce Back Loan Scheme?

CBILSBounce Back Loan Scheme
GuaranteeProvides the lender with a government-backed, partial guarantee (80%) against the outstanding guarantee facility balance (only principal). The portfolio cap has now been removed.Provides the lender with a government-backed, full guarantee (100%) against the outstanding guarantee facility balance (both principal and interest), with no portfolio cap.
Guarantee fee for businessesNo fee.No fee.
Fee charged to lenders for each facilityA fee is charged to lenders for each facility which makes use of the Scheme.No fee to lenders.
Types of facilityFacilities available include term loans, overdrafts, invoice finance and asset finance facilities.Term loan only.
Maximum and minimum value of facilityFollowing the launch of the Bounce Back Loan Scheme the minimum for term loans and overdrafts will be £50,001. Lenders delivering asset or invoice finance facilities only will still be able to provide finance at less than £50,001.

The maximum value of a facility provided under the Scheme is £5m.
The minimum value of a facility provided under the Scheme is £2,000; the maximum is 25% of turnover up to a cap of £50,000.
Interest rate and fees set by lenderInterest and fees are set by accredited lenders and will vary by lender.The interest is set by government at 2.5% per annum. No lender-levied fees.
Repayment termsRepayment terms limited to a maximum of six years for term loan and asset finance facilities up to £5m. For overdrafts and invoice finance facilities, terms will be up to three years.

The government will make a Business Interruption Payment to the lender to cover first 12 months of interest and fees payable.

Principal repayment holidays are at the discretion of the lender.
Repayment terms are six years, but there are no additional fees for early repayment charges.

The government will make a Business Interruption Payment to the lender to cover first 12 months of interest payable.

The borrower has a 12-month principal repayment holiday.
RefinancingRe-financing limited to a maximum of 20% of a lenders’ total CBILS lending. There is no restriction on the total amount of the facility that may consist of refinancing.
Assessment of affordability and viabilityBusinesses must:

• Have a borrowing proposal which the lender would consider viable, were it not for the current pandemic
• Self-certify that it has been adversely impacted by the coronavirus (COVID-19)
• Not have been classed as a ”business in difficulty” on 31 December 2019, if applying to borrow £30,000 or more.

All lending decisions remain fully delegated to lenders.
The borrower is required to self-declare they meet the eligibility criteria for the scheme.

Lenders do not have to assess a business’ affordability or viability. Lenders are not responsible for the borrower’s decision to borrow.
Borrower’s protectionAll existing statutory rights (for example, Consumer Credit Act and FCA protections) apply.Not subject to the many of the usual consumer protections that apply to business lending under £25,000. Borrowers do not have the benefit of protection and remedies that would otherwise be available under the Consumer Credit Act 1974.
Businesses eligibleAvailable to UK-based businesses with annual turnover of up to £45m per year.

Smaller businesses from all sectors can apply for the full amount of the facility. However, fishery, aquaculture and agriculture businesses may not qualify for the full interest and fee payment.
Available to most UK-based businesses, regardless of turnover.

If the business is a “business in difficulty” as of December 31 2019 then businesses in agriculture, aquaculture or fisheries may not qualify for the full amount; and the loan cannot be used for export-related activities.
Personal guaranteesNo personal guarantees for any facilities below £250,000. Other forms of security may still be required by the lender.

Security, including personal guarantees may still be required for facilities above £250,000 but they exclude a borrower’s main home; and recoveries are capped at a maximum of 20% of outstanding balance.
No personal guarantees.

No recovery action can be taken over a borrower’s main home or primary personal vehicle.

For sole traders or partnerships, who do not have the benefit of limited liability, other personal assets may be at risk of recovery action.
 
Top